“I am a model who also works with overseas clients, and I rent a small apartment. I heard rent can be recognized as an expense from 2026. If I also use my home for professional activity, can I claim part of the rent?”
The question has been reworded based on the case presented to the firm. Residential details have been generalized to protect privacy.
The firm's answer
The business portion can be reviewed based on actual use and evidence.
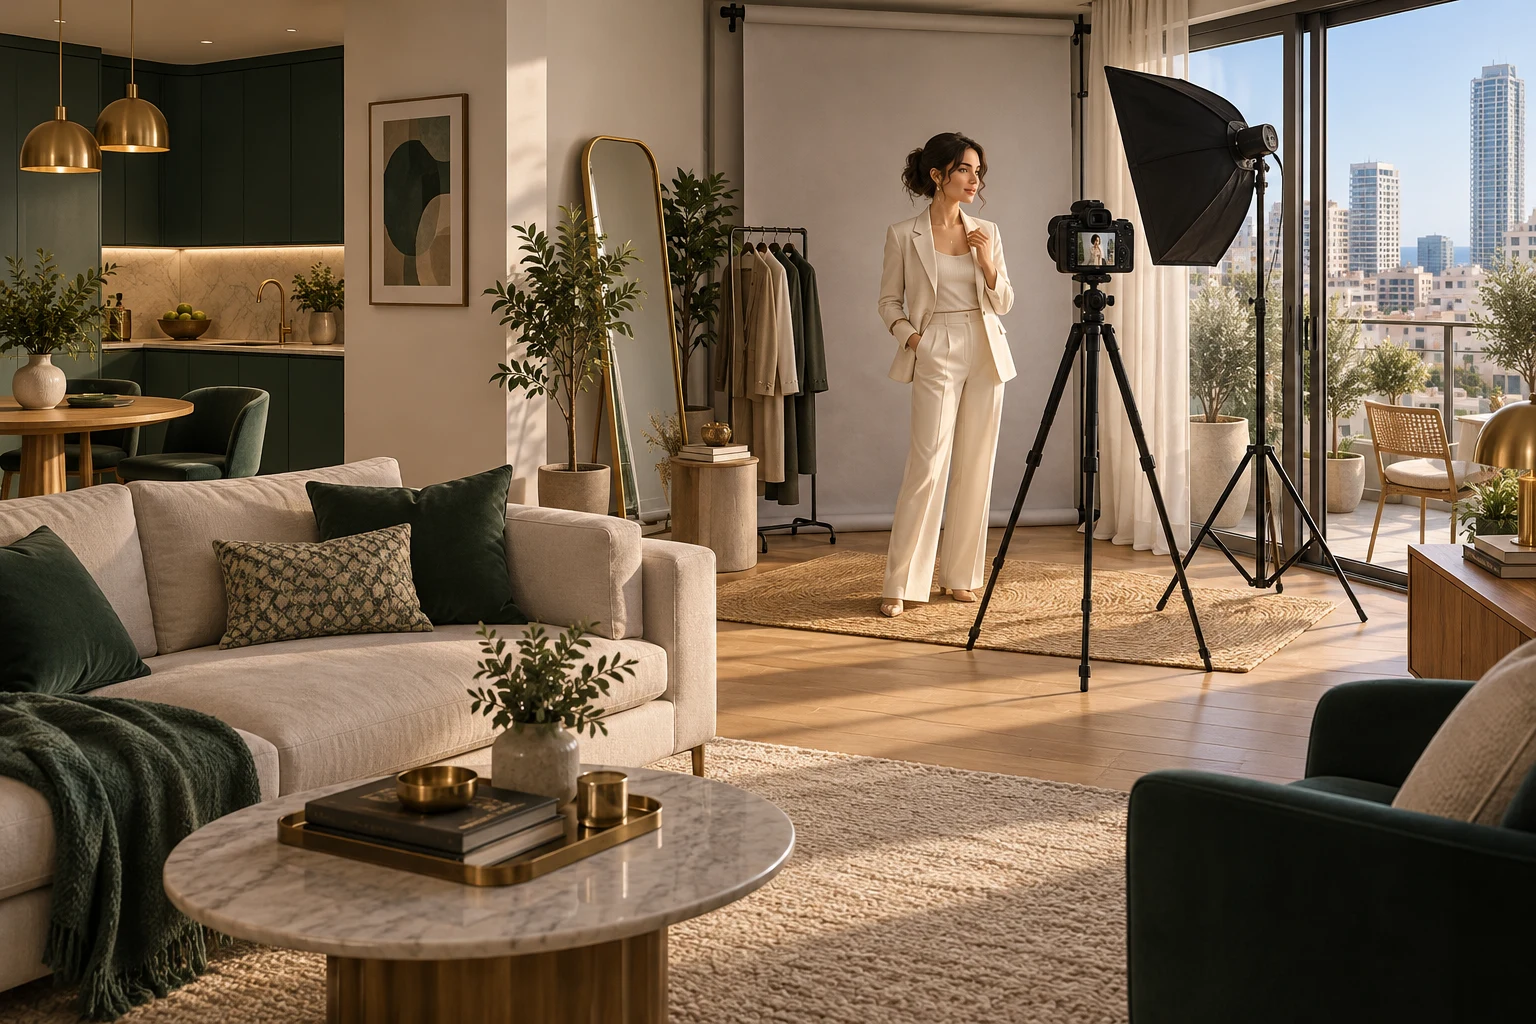
Where part of the apartment is actually used to generate income, such as a work area or professional photography studio, deductibility of the appropriate rent portion can be examined. Private residential expenditure does not become deductible simply because the tenant is self-employed.
In a small apartment, it is particularly important to show which area is used for business and what happens there. Occasional activity at home does not automatically establish a deductible percentage, and there is no fixed percentage suitable for every business.
What should be checked before claiming the expense?
- Connection to income: What professional activity takes place in the apartment, and how does it relate to the business?
- Area and use: Measure and document the business portion. Where an area is also used for living, consider its mixed use rather than treating it as exclusively business-related.
- Documentation: The lease, payment evidence, a description of the work area and suitable records of the business activity.
- Withholding tax: Check separately whether an obligation or exemption exists and how it should be handled. The circular's clarification is not a blanket exemption from withholding and reporting obligations.
Section 17 of the Income Tax Ordinance provides the basis for reviewing expenses incurred to generate income; section 32 restricts private expenses. Section 32A adds conditions concerning withholding tax. All these requirements must be considered together; the new clarification does not automatically approve deducting rent.
Do not claim all the rent as a business expense. Review the evidenced use, separate the private portion and determine the appropriate business portion only after examining the documents.
This explanation concerns Income Tax and does not determine entitlement to deduct input VAT. Working with overseas clients does not, in itself, change the test of business use of the apartment. This is general information requiring individual application with the firm.